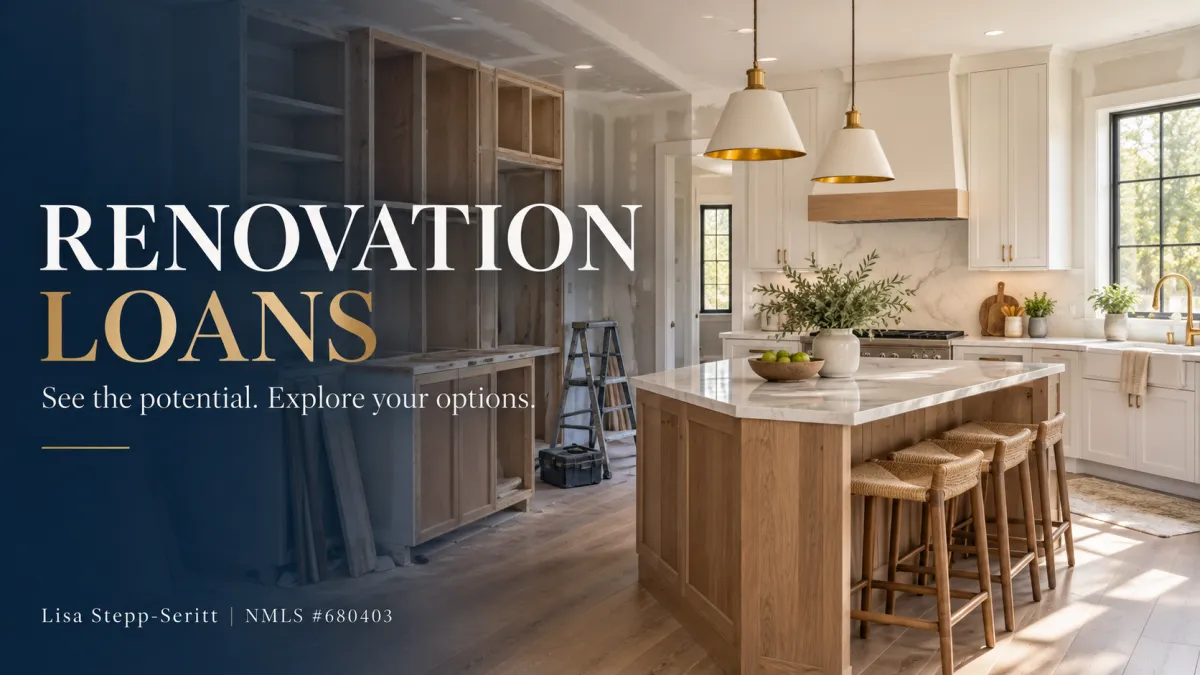
Can You Buy a Fixer-Upper With a VA Renovation Loan?
Love the location. See the potential. But the house needs work.
Before you cross it off your list, ask whether VA renovation financing could fit the property—and your plans.
Can you buy a fixer-upper with a VA loan? Yes. VA-backed purchase loans can be used to buy and improve a home. Through a participating lender, renovation financing may combine the purchase and eligible repairs into one mortgage. The borrower, property and project must meet VA and lender requirements.Source: VA purchase loans
Watch: VA Renovation Loans Explained
Watch my VA renovation financing video here.
Here are the questions to work through before making an offer.
What Is a VA Renovation Loan?
A VA renovation loan, sometimes called a VA rehab loan, generally refers to VA-backed financing that includes eligible improvements as part of the transaction.
The important first step is finding out whether the lender offers a renovation program that fits the proposed work. Offering VA loans does not automatically mean a lender can finance your renovation project.
Start with the property listing and a clear description of the repairs. That gives your lender something specific to evaluate.
Who Can Qualify?
VA purchase financing requires a Certificate of Eligibility, acceptable credit and income, and satisfaction of other applicable underwriting requirements. You must also meet the occupancy requirements for the home.
A Certificate of Eligibility establishes eligibility for the benefit; it does not guarantee mortgage approval.Source: VA eligibility requirements
Which Repairs Can Be Included?
Confirm the proposed work with the lender before assuming it can be financed.
Make two lists: repairs the home appears to need and improvements you would like to make. Then ask:
Which items does this renovation program allow?
Which repairs must be completed to satisfy property requirements?
Are there restrictions on structural work?
What bids, permits and contractor documents are required?
How are unexpected costs or changes handled?
A contractor’s estimate is helpful, but it is not financing approval. Have the scope reviewed before signing renovation agreements or paying deposits.
How Do the Appraisal and Inspection Fit In?
A VA appraisal evaluates value and basic property requirements.It does not replace a home inspection.The VA strongly recommends an inspection to help identify major defects before you purchase.Source: VA homebuying process
For a renovation transaction, ask your lender how the planned work will be considered in the appraisal and what documentation is needed.
Also ask what happens if the supported value is lower than expected. Spending money on improvements does not guarantee the same increase in appraised value.
Five Questions to Ask Before Making an Offer
1. Does this property fit an available renovation program?
Send the listing and repair outline early. A financing conversation is much more useful when it is tied to a specific property.
2. What contractor requirements apply?
Ask about contractor review, written bids, licensing, insurance and permits where applicable. Do not assume you can complete the work yourself.
3. What is my total cash requirement?
Request a written estimate covering closing costs, any required down payment, applicable VA funding fee and project-related costs. “No down payment” should never be interpreted as “no money needed.”Source: VA purchase loan costs
4. How will the renovation timeline work?
Clarify the lender’s requirements for closing, starting work, completing repairs, inspections and releasing renovation funds. Coordinate those expectations with your agent and contractor.
5. Does the finished home fit my budget?
Consider the mortgage payment, taxes, insurance, any homeowners association dues and ongoing maintenance. The goal is a home you can comfortably own after the renovation is finished.
Frequently Asked Questions
Does every VA lender offer renovation financing?
No. Ask specifically about renovation financing and describe the work you want completed.
Can I choose any contractor?
Confirm the program’s contractor requirements before making a commitment. Your preferred contractor and proposed work need to fit the lender’s process.
Can I use this financing solely to buy a vacation rental?
VA purchase financing requires personal occupancy. If your goal is solely an investment property or vacation rental, discuss financing designed for that purpose.Source: VA occupancy requirement
Should I wait until I am under contract to ask about renovations?
Start the conversation before making an offer whenever possible. Reviewing the property and repair plan early can help your agent structure a more realistic timeline.
Found a Home With Potential? Let’s Talk Before You Make the Offer.
You do not need every answer before starting the conversation. Bring the listing, the asking price and a rough idea of the work you have in mind.
I’ll help you identify the financing questions to address and explore whether an available program could fit your plans.
VisitLisaStepp.comand select “Book a Strategy Call” to discuss your financing options.
About the Author
Lisa Stepp-Seritt is a Senior Loan Officer with Mpire Financial with approximately 25 years of mortgage-industry experience. She helps homebuyers and real estate investors understand financing options and prepare for their next purchase.
Lisa Stepp-Seritt | NMLS #680403
Mpire Financial | NMLS #2108504
Equal Housing Opportunity
Educational information only; not a commitment to lend. All financing is subject to borrower eligibility, credit, income, property and underwriting approval. Program availability, eligible improvements, contractor requirements and terms vary by lender and state. Not affiliated with or endorsed by the Department of Veterans Affairs.
